
Malaysia SST Industry Guides — Timeline, Content and Amendments (2018–2026)
马来西亚 SST 行业指南——时间线、内容与修订(2018–2026)

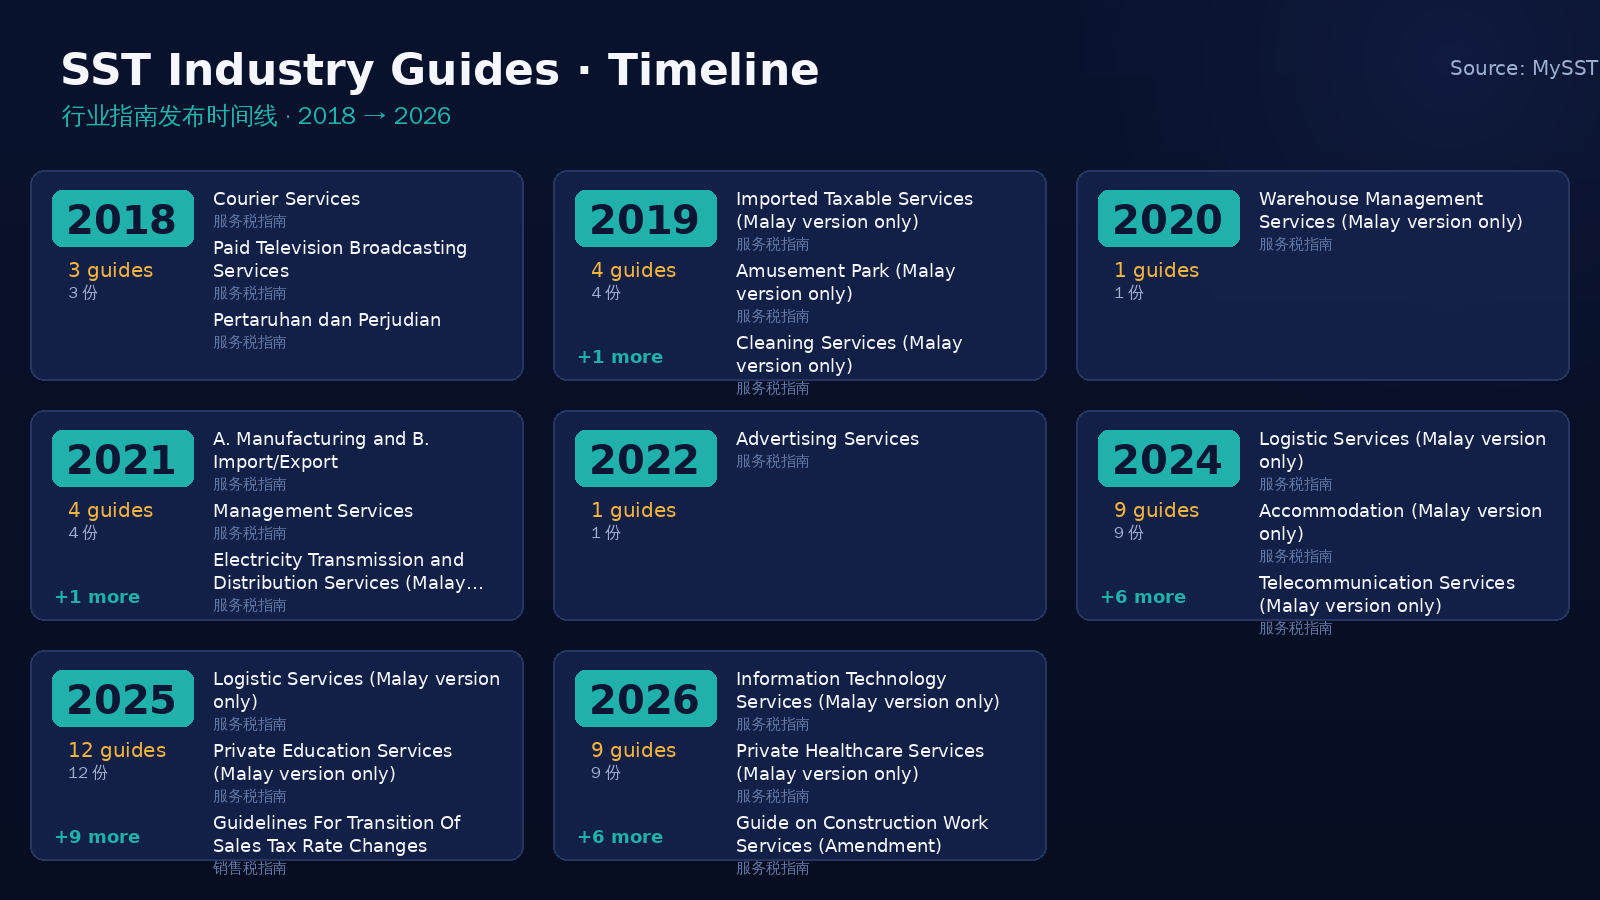
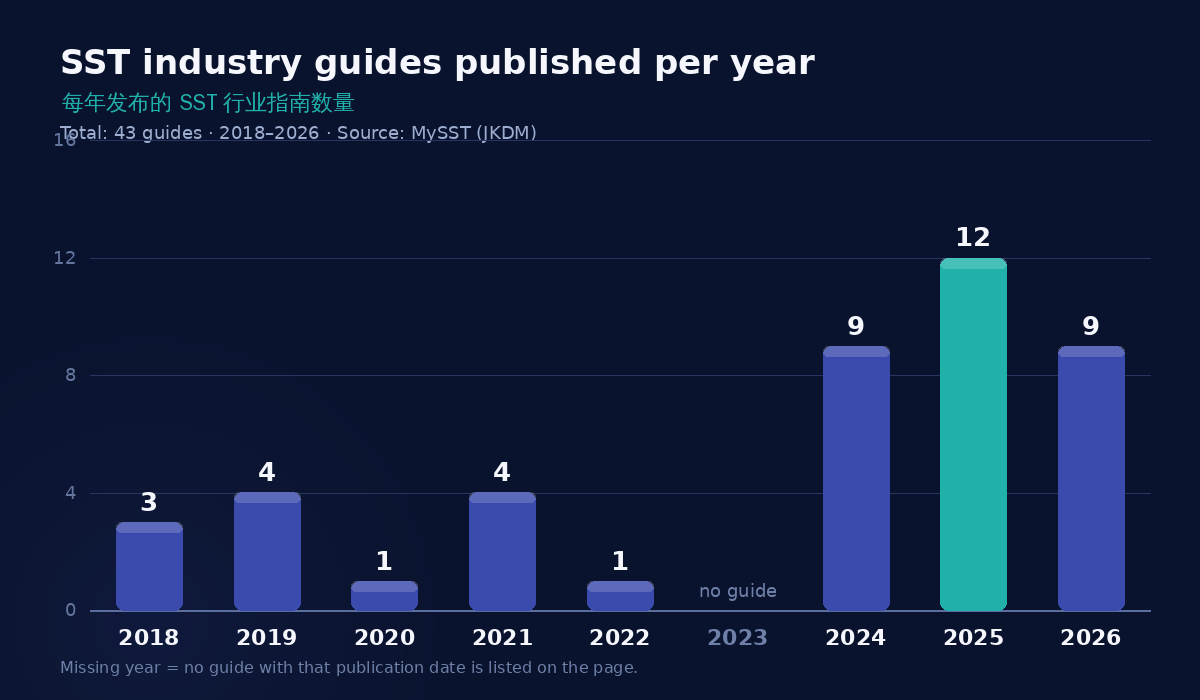
The SST side of the MySST Industry Guides collection is messier than the e-Invoice list: 43 guides spread over eight years, many published only in Malay, several superseded by later versions and a handful that revise an earlier guide rather than introduce a new one. This post therefore reads the list from the oldest guide (21 August 2018) forward, so that each expansion of the service tax base — the 2018 launch, the January 2019 additions, the 26 February 2024 broadening, the 1 July 2025 finance-sector changes and the 2026 refinements — can be seen in the order in which taxpayers had to absorb it. Each entry below gives the publication date and title exactly as listed, followed by a summary of what that guide actually contains, drawn from its extracted text. Items marked AMENDMENT — or 修订—— are re-issues or amendments: for those, only the amended part described in the extracted text is summarised instead of rewriting the whole guide. Where a guide is listed as Malay version only, the Malay content has been read and translated into English before being put into Chinese.
MySST 行业指南这一侧的 SST 资料比电子发票清单更为杂乱:43 份指南横跨八年,许多只以马来文发布,若干份已被后续版本取代,还有一小部分是对早前指南的修订而非推出新指南。因此,本文按从最旧的指南(2018 年 8 月 21 日)向最新的顺序阅读,以便看清服务税征税范围每一次扩大的先后次序——2018 年开征、2019 年 1 月新增项目、2024 年 2 月 26 日的扩大、2025 年 7 月 1 日的金融领域调整以及 2026 年的细化——纳税人正是按这个顺序承受这些变化的。以下每一条都给出清单上的发布日期与标题原文,随后根据该指南被提取的正文,概述其实际内容。标注“修订——”(AMENDMENT —)的条目属于重新发布或修订件:对这些条目,只概述被提取正文中所述的修订部分,而不重写整份指南。凡标注为仅马来文版本的指南,均先阅读马来文内容并译为英文,再译为中文。
21-08-2018 — Courier Services. Effective 1 September 2018, courier delivery services provided under prescribed circumstances became taxable under Group I, Item 6, First Schedule of the Service Tax Regulations 2018. The guide fixes its terminology: a "courier service" is a postal service provided in an expedited manner with track-and-trace, as defined in regulation 2 of the Postal Services (Licensing) Regulations 2015, while "postal services" means the collection, transmission and delivery of any postal article under the Postal Services Act 2012. It also defines a "designated area" as Labuan, Langkawi and Tioman (Section 47, Service Tax Act 2018) and a "special area" as any free zone, licensed warehouse or licensed manufacturing warehouse under the Act. These definitions matter because they mark off the geography in which the tax treatment can differ from ordinary Malaysia.
21-08-2018 — 快递服务(Courier Services)。自 2018 年 9 月 1 日起,在规定情形下提供的快递递送服务,依 2018 年服务税条例附表一第 I 组第 6 项成为应税服务。指南明确其术语:“快递服务”指以加快方式提供并具备追踪查询功能的邮政服务(依 2015 年邮政服务(发牌)条例第 2 条的定义);而“邮政服务”指依 2012 年邮政服务法对任何邮件的收寄、传送与投递。指南亦将“指定区域”界定为纳闽、兰卡威与刁曼(2018 年服务税法第 47 条),将“特别区域”界定为该法下的任何自由区、持牌仓库或持牌制造仓库。这些定义之所以重要,是因为它们划定了税务处理可能不同于马来西亚一般地区的范围。
21-08-2018 — Paid Television Broadcasting Services. Effective 1 September 2018, paid television broadcasting services provided under prescribed circumstances are taxable under Group I, Item 2, First Schedule of the Service Tax Regulations 2018. The guide explains that paid television broadcasting is one of the broadcasting services licensed by the Malaysian Communications and Multimedia Commission (MCMC). It is commonly called subscription television, premium television or pay-TV, and consists of the transmission of video, audio and all other programming services to subscribers. The guide notes that the term itself carries the meaning assigned to it under the Communications and Multimedia (Licensing) Regulations 2000.
21-08-2018 — 付费电视广播服务(Paid Television Broadcasting Services)。自 2018 年 9 月 1 日起,在规定情形下提供的付费电视广播服务,依 2018 年服务税条例附表一第 I 组第 2 项成为应税服务。指南说明,付费电视广播是马来西亚通讯与多媒体委员会(MCMC)发牌的各类广播服务之一。它通常被称为订阅电视、付费电视或 pay-TV,指向订户传送视频、音频及所有其他节目服务。指南指出,该术语本身采用 2000 年通讯与多媒体(发牌)条例所赋予的含义。
04-09-2018 — Pertaruhan dan Perjudian (Betting and Gambling). No PDF is published on the page for this guide; only the title is available. Its Malay title covers betting and gambling, the activity group otherwise taxed under the service tax framework. Because nothing was extracted from the page, no scope, rate, threshold or registration detail can be confirmed for this particular guide. Readers looking for the betting and gambling treatment must therefore rely on the published title and on the general service tax provisions rather than on text from this guide, and no amendment content is described here since none could be read.
04-09-2018 — 博彩与赌博(Pertaruhan dan Perjudian)。该指南的页面上未发布 PDF,仅可取得标题。其马来文标题涵盖博彩与赌博——在服务税框架下另行征税的活动类别。由于页面未能提取任何正文,本指南的范围、税率、门槛或注册细节均无法确认。因此,查找博彩与赌博税务处理的读者只能依据所公布的标题及一般服务税条文,而不能依据本指南的正文;由于无法读取任何修订内容,此处亦不描述修订。
09-01-2019 — Imported Taxable Services (Malay version only). The guide sets out the charging provision: service tax is imposed and levied on any taxable service provided in Malaysia by a registered person in the course of business, or on any imported taxable service. From 1 January 2019, imported taxable services became subject to service tax. Any person carrying on business in Malaysia — including in a designated area or special area — who acquires a taxable service from a service provider outside Malaysia must pay service tax. For this purpose "any person" covers businesses whether or not they are registered under the Service Tax Act 2018, and an imported taxable service is any service prescribed as taxable in the First Schedule of the Service Tax Regulations 2018 that is supplied by a foreign provider.
09-01-2019 — 进口应税服务(Imported Taxable Services,仅马来文版本)。指南阐述征税条款:对在马来西亚由注册人在经营业务过程中提供的任何应税服务,或对任何进口应税服务,征收并课征服务税。自 2019 年 1 月 1 日起,进口应税服务须缴服务税。任何在马来西亚(包括在指定区域或特别区域内)经营业务的人,凡从马来西亚境外的服务提供者取得应税服务,均须缴纳服务税。为此,“任何人”涵盖不论是否依 2018 年服务税法注册的企业;而进口应税服务指由境外提供者供应、并在 2018 年服务税条例附表一中被规定为应税的任何服务。
22-01-2019 — Amusement Park (Malay version only). From 1 January 2019, the provision of amusement park services is subject to service tax under Group I, Item 11, First Schedule of the Service Tax Regulations 2018. The guide defines an "Amusement Park" as a place with any building, premises or structure, temporary or permanent, containing various attractions including rides, games and fun activities, with or without a theme, which people are allowed to enter on payment of an admission charge. It also defines a "Special Area" as any free zone, licensed warehouse, licensed manufacturing warehouse and joint development area (Section 52 of the Service Tax Act). The admission-charge element in the definition is the practical test of whether a site falls within the tax.
22-01-2019 — 游乐园(Amusement Park,仅马来文版本)。自 2019 年 1 月 1 日起,提供游乐园服务依 2018 年服务税条例附表一第 I 组第 11 项须缴服务税。指南将“游乐园”定义为:其上有任何建筑物、场所或构筑物(无论临时或永久),内含各类游乐设施,包括乘骑设施、游戏及娱乐活动(无论有无主题),并允许人们缴付入场费进入的地方。指南亦将“特别区域”定义为任何自由区、持牌仓库、持牌制造仓库及联合发展区(服务税法第 52 条)。定义中的“入场费”要素,是判断某一场所是否落入征税范围的实际标准。
22-02-2019 — Cleaning Services (Malay version only). From 1 January 2019, any person providing cleaning services in relation to goods, land, or commercial or industrial buildings is subject to service tax under Item 13, Group I, First Schedule of the Service Tax Regulations 2018. Cleaning services are defined as any cleaning activity carried out manually, chemically or mechanically to remove dirt or other unwanted matter from an item, building or location. The guide works through examples: a goldsmith shop that offers to wash jewellery using particular chemicals is providing a cleaning service, and a company appointed by a ship line agency to clean up an oil spill is providing cleaning of land. The examples show that the tax attaches to the cleaning activity itself rather than to the type of customer.
22-02-2019 — 清洁服务(Cleaning Services,仅马来文版本)。自 2019 年 1 月 1 日起,任何就物品、土地或商业或工业建筑物提供清洁服务的人,依 2018 年服务税条例附表一第 I 组第 13 项须缴服务税。清洁服务被定义为以人工、化学或机械方式进行的任何清洁活动,用以去除物品、建筑物或地点上的污垢或其他不需要的物质。指南以实例说明:金店使用特定化学品提供珠宝清洗服务,即属提供清洁服务;一家受船务代理公司委任清理漏油的公司,则属提供土地清洁服务。这些例子显示,税项附着于清洁活动本身,而非客户类型。
05-03-2019 — Freight Courier Services (Malay version only). Effective 1 September 2018, the provision of courier delivery services under prescribed circumstances is subject to service tax under Group I, Item 6, First Schedule of the Service Tax Regulations 2018. The terms are fixed in the same way as in the original courier guide: a courier service is a postal service provided in an expedited manner with track-and-trace under regulation 2 of the Postal Services (Licensing) Regulations 2015; postal services means the collection, transmission and delivery of a postal article under the Postal Services Act 2012; a designated area is Labuan, Langkawi and Tioman under Section 47 of the Service Tax Act 2018; and a special area is any free zone, licensed warehouse or licensed manufacturing warehouse. Readers should note that although the guide is dated 2019, the tax itself applies from 1 September 2018.
05-03-2019 — 货运快递服务(Freight Courier Services,仅马来文版本)。自 2018 年 9 月 1 日起,在规定情形下提供的快递递送服务,依 2018 年服务税条例附表一第 I 组第 6 项须缴服务税。术语的界定与原快递指南相同:快递服务指依 2015 年邮政服务(发牌)条例第 2 条以加快方式提供并具备追踪查询的邮政服务;邮政服务指依 2012 年邮政服务法收寄、传送与投递邮件;指定区域指 2018 年服务税法第 47 条下的纳闽、兰卡威与刁曼;特别区域指任何自由区、持牌仓库或持牌制造仓库。读者应注意,尽管指南日期为 2019 年,税项本身自 2018 年 9 月 1 日起适用。
06-10-2020 — Warehouse Management Services (Malay version only). Service tax on warehouse management services took effect on 1 September 2018, and any person providing management services is subject to it under Item 9, column (1), Group G, First Schedule of the Service Tax Regulations 2018. The guide records that amendments were made to clarify further the activities falling within the management services category, effective 1 January 2019, and states that those amendments do not affect the service provider's liability to comply with all provisions of the Service Tax Act 2018 in force from 1 September 2018. Warehouse management services are defined as services provided by a warehouse operator covering the arrangement and coordination of any activities provided on a continuing basis — the definition that anchors the whole guide's scope.
06-10-2020 — 仓库管理服务(Warehouse Management Services,仅马来文版本)。仓库管理服务的服务税自 2018 年 9 月 1 日起生效,任何提供管理服务的人依 2018 年服务税条例附表一第 G 组第 (1) 栏第 9 项须缴此税。指南记载,为进一步厘清属于管理服务类别的活动,曾作出修订并于 2019 年 1 月 1 日生效;指南并说明,该等修订不影响服务提供者遵守自 2018 年 9 月 1 日起生效的 2018 年服务税法全部规定的责任。仓库管理服务被定义为仓库营运者所提供的、涵盖持续性地安排与协调任何活动的服务——这一定义支撑整份指南的范围。
01-01-2021 — A. Manufacturing and B. Import/Export. Manufacturers of taxable goods whose sales value exceeds RM500,000 within a 12-month period are required to register under Section 12 of the Sales Tax Act 2018. Manufacturers with sales value of RM500,000 and below may register voluntarily under Section 14. Manufacturers operating as subcontractors whose total labour charge for subcontract work exceeds RM500,000 within 12 months are likewise required to register under Section 12. The guide also restates the principles in Section 3 of the Sales Tax Act 2018 on the definition of manufacturing, which is the threshold question for whether a process falls within sales tax at all.
01-01-2021 — A. 制造业与 B. 进出口(A. Manufacturing and B. Import/Export)。在 12 个月期间内应税货物销售额超过 500,000 令吉的制造商,须依 2018 年销售税法第 12 条注册。销售额为 500,000 令吉及以下的制造商,可依第 14 条自愿注册。以分包商身份经营、且 12 个月内分包工程总劳务费超过 500,000 令吉的制造商,同样须依第 12 条注册。指南亦重述 2018 年销售税法第 3 条关于“制造”定义的原则——这是判断某一工序是否落入销售税范围的门槛问题。
04-08-2021 — Management Services. Under subsection 10(2) of the STA 2018, the Minister of Finance determined that the service tax rate rose from 6% to 8% effective 1 March 2024 on all taxable services except those specified in the First Schedule and Second Schedule of the Service Tax (Rate of Tax) Order 2018. The provision of management services is accordingly subject to service tax at 8% from 1 March 2024, and the guide directs readers to the transition guide for the transitional treatment of rate changes. The taxable services listed under item (i), column (2), Group G, First Schedule of the STR 2018 include project management services for the whole or part of a project, carried out by any person managing a project in full or in part.
04-08-2021 — 管理服务(Management Services)。依 2018 年服务税法第 10(2) 条,财政部长决定自 2024 年 3 月 1 日起,对所有应税服务的服务税税率由 6% 提高至 8%,惟 2018 年服务税(税率)令附表一及附表二所列服务除外。据此,提供管理服务自 2024 年 3 月 1 日起按 8% 缴纳服务税,指南并指引读者参阅过渡指南以了解税率变更的过渡处理。2018 年服务税条例附表一第 G 组第 (2) 栏第 (i) 项所列应税服务,包括由任何人就整个或部分项目所进行的项目管理服务。
04-08-2021 — Electricity Transmission and Distribution Services (Malay version only). The guide covers taxable services under Item 9, Group I, First Schedule of the Service Tax Regulations 2018 — the transmission and distribution of electricity. In its FAQ it addresses whether an entity holding a Public Distribution Licence (Lesen Awam Pengagihan, LAP) is subject to service tax, and answers that it is not: an LAP holder under Section 9(1)(b) of the Electricity Supply Act 1990 buys electricity from a main supplier such as TNB and distributes it directly to commercial users without any electricity transmission service being involved. The licence-based distinction is therefore the practical dividing line between a taxable transmission or distribution service and an exempt distribution activity.
04-08-2021 — 电力输送与配电服务(Electricity Transmission and Distribution Services,仅马来文版本)。指南涵盖 2018 年服务税条例附表一第 I 组第 9 项下的应税服务——电力的输送与配电。其常见问题部分探讨持有公共配电执照(Lesen Awam Pengagihan,LAP)的实体是否须缴服务税,答案是“否”:依 1990 年电力供应法第 9(1)(b) 条持有 LAP 者,向主要供应商(如国能 TNB)购电并直接配电给商业用户,过程中不涉及电力输送服务。因此,以执照为界,正是应税输送或配电服务与免税配电活动之间的实际分界线。
31-10-2021 — Professional Services. Effective 1 September 2018, the provision of professional services listed in Group G, First Schedule of the Service Tax Regulations 2018 is subject to service tax. The guide enumerates twelve categories: legal services; legal services on Islamic matters; accounting services; surveying services; engineering services; architectural services; consultancy, training and coaching services; information technology services; management services; employment services; safety or security services; and digital services. It then goes through the individual categories, beginning with legal services, which it defines as the rendering of legal advice and the dispensing of legal representation in matters pertaining to laws. The list is the single most useful page in the SST set for working out whether a professional firm is in scope.
31-10-2021 — 专业服务(Professional Services)。自 2018 年 9 月 1 日起,提供 2018 年服务税条例附表一第 G 组所列专业服务须缴服务税。指南列举十二类:法律服务;伊斯兰事务法律服务;会计服务;测量服务;工程服务;建筑服务;咨询、培训与辅导服务;信息技术服务;管理服务;雇员服务;安全或保安服务;以及数字服务。指南随后逐一说明各类别,并以法律服务开头,将其定义为就法律事务提供法律意见及提供法律代表。这份清单是整个 SST 资料中判断某专业事务所是否在征税范围内最有用的一页。
19-01-2022 — Advertising Services. The guide is written in question-and-answer form and works through the place-of-supply questions that decide whether advertising is taxable. Advertising services provided outside Malaysia, or outside the scope of the provision of advertising services in Malaysia, are not subject to service tax. A media owner located in a designated area who provides billboard advertising in Langkawi is not liable, because advertising services provided within or between designated areas (Langkawi, Tioman and Labuan) are not subject to service tax and need not be accounted for. A service tax registered advertising agency in Malaysia appointed by a foreign company to advertise its product for the local market is, however, subject to service tax, since it provides advertising services in Malaysia.
19-01-2022 — 广告服务(Advertising Services)。指南以问答形式撰写,逐一处理决定广告是否应税的供应地问题。在马来西亚境外提供的广告服务,或不属马来西亚广告服务提供范围者,无须缴服务税。位于指定区域、在兰卡威提供广告牌广告的媒体所有者无须缴税,因为在指定区域之内或之间(兰卡威、刁曼与纳闽)提供的广告服务不属应税,亦无须申报。然而,一家在马来西亚注册服务税的广告代理,若受外国公司委任为其产品在本地市场投放广告,则须缴服务税,因其是在马来西亚提供广告服务。
26-02-2024 — Logistic Services (Malay version only). Any person providing logistics services is categorised as a taxable person under Group J, First Schedule of the Service Tax Regulations 2018. For service tax purposes, warehouse management services, express courier services and customs agent services have been consolidated within the taxable logistics services group, and the guide's Table 1 sets out the effective dates: warehouse management 1 September 2018; express courier licensed under Section 10 of the Postal Services Act 2012, 1 September 2018; customs agent, 1 September 2018; and logistics itself, 26 February 2024. Service tax on logistics services is not imposed on duties, taxes, levies, charges or any gazetted fees. This is the guide that explains why the same paragraph and table also appear in the later, re-dated logistics guides.
26-02-2024 — 物流服务(Logistic Services,仅马来文版本)。任何提供物流服务的人,在 2018 年服务税条例附表一第 J 组下被归类为应税人。就服务税而言,仓库管理服务、特快快递服务与报关代理服务已被并入应税的物流服务组;指南表一列明生效日期:仓库管理为 2018 年 9 月 1 日;依 2012 年邮政服务法第 10 条持牌的特快快递为 2018 年 9 月 1 日;报关代理为 2018 年 9 月 1 日;物流服务本身为 2024 年 2 月 26 日。物流服务的服务税不对关税、税务、征费、收费或任何宪报公布的费用征收。正是这份指南解释了为何同一段落与表格也出现在日期较后的物流指南中。
26-02-2024 — Accommodation (Malay version only). Under Group A, accommodation premises means hotels, inns, lodging houses, service apartments, homestays or similar establishments. The guide then carves out accommodation provided by the Federal Government or a State Government; by a statutory body or local authority; by a private educational institution registered under the Education Act 1996 [Act 550] or the Private Higher Educational Institutions Act 1996 [Act 555]; or by a religious or welfare body registered with the Registrar of Societies or under any written law regulating such bodies, for religious or welfare activities. The exclusions, not the inclusions, do most of the work in practice, since they decide which operators never register at all.
26-02-2024 — 住宿(Accommodation,仅马来文版本)。在第 A 组下,住宿场所指酒店、客栈、寄宿舍、服务式公寓、民宿或类似场所。指南随后排除由下列各方提供的住宿:联邦政府或州政府;法定机构或地方当局;依 1996 年教育法【第 550 号法令】或 1996 年私立高等教育机构法【第 555 号法令】注册的私立教育机构;或依马来西亚社团注册官或任何规范此类机构的成文法注册的宗教或福利团体,且用于宗教或福利活动者。在实践中真正起决定作用的是排除条款而非纳入条款,因为它们决定哪些经营者根本无须注册。
27-02-2024 — Telecommunication Services (Malay version only). The extracted text of this guide opens with the standard RMCD disclaimer rather than the substantive chapters: it is intended to give a general understanding of the relevant treatment under service tax and of taxpayers' obligations, does not comprehensively address every possible tax issue, and RMCD accepts no responsibility for errors, inaccuracies or financial loss arising from its use, with all information current at the time of preparation and subject to change. What survives in the extraction is its table of contents, which shows that the guide is organised around basic telecommunications, confirming that the guide deals with telecommunication services rather than with any other category. No rate, threshold or item number is visible in the extracted portion, so none is stated here.
27-02-2024 — 电信服务(Telecommunication Services,仅马来文版本)。本指南被提取的正文以关税局(RMCD)的标准免责声明开篇,而非实质章节:其意在让读者概括了解服务税下的相关处理及纳税人的义务,并非全面处理所有可能出现的税务问题;RMCD 对因使用本指南而产生的错误、不准确或财务损失概不负责;所有资料以编制时为准,并可能随时变更。提取内容中保留下来的是其目录,显示指南以“基础电信”为主轴编排,从而确认本指南处理的是电信服务而非其他类别。被提取的部分未见任何税率、门槛或项目编号,故此处不予列明。
29-02-2024 — Consultancy, Training, and Mentoring Services (Malay version only). Under Item 7, Group G, First Schedule of the Service Tax Regulations 2018 and the Service Tax Regulations (Amendment) (No. 3) 2018, any person providing consultancy, training or mentoring services is treated as a taxable person. The guide then lists the categories of persons who are not treated as taxable persons even though they provide such services: companies approved with contract research and development company status, or defined as such, under Section 2 of the Promotion of Investments Act 1986 and research institutes approved under Section 34B of the Income Tax Act 1967; the Federal Government; State Governments; and local authorities. The exclusion list is the operative part of this guide for public-sector and R&D providers.
29-02-2024 — 咨询、培训与辅导服务(Consultancy, Training, and Mentoring Services,仅马来文版本)。依 2018 年服务税条例附表一第 G 组第 7 项及 2018 年服务税条例(修订)(第 3 号),任何提供咨询、培训或辅导服务的人均被视为应税人。指南随后列出即使提供此类服务亦不被视为应税人的类别:依 1986 年促进投资法第 2 条获批准具合约研发公司地位或被如此界定的公司,以及依 1967 年所得税法第 34B 条获批准的研究机构;联邦政府;州政府;以及地方当局。对公共部门与研发提供者而言,这份排除清单才是本指南的要点。
29-03-2024 — Maintenance or Repair Services (Malay version only). The guide works through a preventive maintenance contract, setting out the work that a company must carry out: inspecting fan bearings and assessing whether lubricating oil is needed, inspecting the suction compressor and pressure relief, cleaning and maintaining air filters, ensuring filters are odour-free and cleaned, ensuring evaporator coils are kept clean and closed, vacuuming the drainage system, checking the outer condenser coil and routinely testing and reviewing the system. These tasks are to be performed once every two months. If a fault arises, the company must file a damage report stating the equipment or spare parts requiring replacement, and any repair activity and replacement of spare parts must be approved by the National Museum Department; the contract price excludes the cost of repairs and replacement parts. The example shows how the tax base is confined to the maintenance service rather than the parts.
29-03-2024 — 保养或维修服务(Maintenance or Repair Services,仅马来文版本)。指南以一份预防性保养合同为例,列明公司须执行的工作:检查风扇轴承并评估是否需要加注润滑油、检查吸气压缩机与泄压情况、清洁并保养空气滤网、确保滤网无异味且已清洁、确保蒸发器盘管保持清洁及封闭、以真空清理排水系统、检查外部冷凝盘管并定期测试与检视系统。上述工作须每两个月进行一次。若发生故障,公司须提交损坏报告,说明需要更换的设备或零件;任何维修活动及零件更换均须获国家博物馆局批准;合同价格不含维修及更换零件的费用。此例显示税基仅限于保养服务本身,而不包括零件。
19-04-2024 — Food and Beverages (Malay version only). Effective 1 September 2018, the provision of food and beverages is subject to service tax under Group B, First Schedule of the Service Tax Regulations 2018. For the purpose of the guide, a food and beverage operator is any person operating a restaurant, bar, snack bar, canteen, coffee house or any other place providing food and beverages, whether consumed on the premises or taken away, excluding canteens located within educational institutions and canteens operated by religious bodies or institutions; it also covers any person providing catering services. The worked example concerns De'Enak Enterprise, which obtained a contract from the Ministry of Education to supply cooked food — illustrating how institutional catering is brought into the taxable scope.
19-04-2024 — 食品与饮料(Food and Beverages,仅马来文版本)。自 2018 年 9 月 1 日起,提供食品与饮料依 2018 年服务税条例附表一第 B 组须缴服务税。就本指南而言,餐饮经营者指经营餐厅、酒吧、小食店、食堂、咖啡店或任何其他提供食品与饮料(无论堂食或外带)场所的任何人,但不包括设于教育机构内的食堂,以及由宗教团体或机构经营的食堂;亦涵盖任何提供餐饮外烩服务的人。指南的实例涉及 De'Enak Enterprise,该公司取得教育部供应熟食的合约——说明机构外烩服务如何被纳入应税范围。
14-05-2024 — Employment Services (Malay version only). A registered person providing taxable employment services must issue an invoice and charge service tax on the taxable services supplied, and must do so on the actual value of the taxable services provided. Service tax is imposed on the value of the employment services excluding expenses that may be claimed back from the customer without any mark-up. The guide lists the reimbursable expenses that qualify, provided they are accompanied by supporting documents: emoluments, levy fees, travel fare to Malaysia, work permits and insurance fees. The list matters because it determines the difference between the invoiced amount and the value on which the 6% or 8% rate is actually applied.
14-05-2024 — 雇员服务(Employment Services,仅马来文版本)。提供应税雇员服务的注册人须开具发票,并就所供应的应税服务征收服务税,且须按所提供应税服务的实际价值计征。服务税按雇员服务的价值计征,但不包括可不加价向客户索回的费用。指南列出符合条件的可报销费用,前提是附有证明文件:薪酬、征费、前往马来西亚的旅费、工作准证及保险费。这份清单之所以重要,是因为它决定了开票金额与实际适用 6% 或 8% 税率的计税额之间的差额。
30-05-2024 — Customs Agent Services (Malay version only). From 1 September 2018, the provision of services for the release of goods from Customs control (customs agent services) became subject to service tax under Item 3, Group I, First Schedule of the Service Tax Regulations 2018. From 26 February 2024, customs agent services were moved into Logistics Services under Item 2, Group J, First Schedule of the same Regulations. The service tax rate charged on customs agent services is 6%. Under Section 90 of the Customs Act 1967, a customs agent is appointed by an importer or exporter to carry out any customs transaction on their behalf, and customs agent services cover forwarding agents, shipping agents and freight forwarders. This guide is the clearest illustration of the 2024 re-grouping, since it tracks the same service across two different Groups and items.
30-05-2024 — 报关代理服务(Customs Agent Services,仅马来文版本)。自 2018 年 9 月 1 日起,提供使货物脱离关税管制的服务(报关代理服务)依 2018 年服务税条例附表一第 I 组第 3 项须缴服务税。自 2024 年 2 月 26 日起,报关代理服务被移入同一服务税条例附表一第 J 组第 2 项的物流服务。报关代理服务所适用的服务税税率为 6%。依 1967 年关税法第 90 条,报关代理由进口商或出口商委任,代其办理任何关税事务;报关代理服务涵盖货运代理、船务代理及运输报关行。本指南最能说明 2024 年的重新归类,因为它追踪同一项服务横跨两个不同的组别与项目。
30-05-2024 — Domestic Flight (Malay version only). From 1 September 2018, under Group I, Item 11, First Schedule of the Service Tax Regulations 2018, the provision of domestic flights under prescribed conditions is subject to service tax. The guide surveys the aviation industry, describing aviation services as three things: the carriage of passengers, mail or cargo for hire or reward by air or using any aircraft between two or more places at least one of which is in Malaysia; the provision of any ground handling services in Malaysia; and the operation of an aerodrome in Malaysia for the landing and departure of aircraft engaged in the carriage of passengers, mail or cargo for hire or reward. The "at least one place in Malaysia" test in the carriage limb is what distinguishes domestic from international carriage.
30-05-2024 — 国内航班(Domestic Flight,仅马来文版本)。自 2018 年 9 月 1 日起,依 2018 年服务税条例附表一第 I 组第 11 项,在规定条件下提供国内航班须缴服务税。指南概述航空业,将航空服务描述为三类:以航空器在两个或以上地点之间(其中至少一个地点位于马来西亚)为租用或报酬而运送乘客、邮件或货物;在马来西亚提供任何地勤服务;以及在马来西亚操作机场,供为租用或报酬从事客运、邮件或货运的航空器起降。“至少一个地点位于马来西亚”这一要件,正是区分国内运输与国际运输的关键。
06-06-2025 — Logistic Services (Malay version only). Any person providing logistics services is categorised as a taxable person under Group J, First Schedule of the Service Tax Regulations 2018. Warehouse management services, express courier services and customs agent services have been consolidated into the taxable logistics services group, and Table 1 gives the effective dates service by service: warehouse management, 1 September 2018; express courier licensed under Section 10 of the Postal Services Act 2012, 1 September 2018; customs agent, 1 September 2018; and logistics, 26 February 2024. Service tax on logistics services is not imposed on duties, taxes, levies, charges or any gazetted fees. The 2025 publication carries the same substantive consolidation as the 2024 version, re-dated 6 June 2025.
06-06-2025 — 物流服务(Logistic Services,仅马来文版本)。任何提供物流服务的人,在 2018 年服务税条例附表一第 J 组下被归类为应税人。仓库管理服务、特快快递服务与报关代理服务已被并入应税的物流服务组;表一按服务逐一列出生效日期:仓库管理为 2018 年 9 月 1 日;依 2012 年邮政服务法第 10 条持牌的特快快递为 2018 年 9 月 1 日;报关代理为 2018 年 9 月 1 日;物流服务为 2024 年 2 月 26 日。物流服务的服务税不对关税、税务、征费、收费或任何宪报公布的费用征收。2025 年版载有与 2024 年版相同的实质合并内容,日期更新为 2025 年 6 月 6 日。
09-06-2025 — Private Education Services (Malay version only). The provision of education-related services to non-citizens by higher education institutions registered under the Universities and University Colleges Act 1971, the Private Higher Educational Institutions Act 1996 and the Education Act 1996, and by language centres registered under the Education Act 1996, is subject to service tax on tuition fees; registration fees; admission charges; co-curricular charges; books and study materials charges; teaching aids or facilities charges; and any other charges or fees relating to education imposed by the institution. The worked example is LinguaPro Academy Language Centre, a private language centre in Kuala Lumpur providing French language education, whose total fees charged to non-citizens are RM40,000 per annum, and those language education services to non-citizens are taxable under Item 3, Group M, First Schedule of the Service Tax Regulations. The Malay-only version carries the same worked example as the English version published four days later.
09-06-2025 — 私立教育服务(Private Education Services,仅马来文版本)。由依 1971 年大学与大学学院法、1996 年私立高等教育机构法及 1996 年教育法注册的高等教育机构,以及依 1996 年教育法注册的语言中心,向非公民提供教育相关服务,须就下列项目缴纳服务税:学费;注册费;入学费;课外活动费;书籍与学习材料费;教具或设施费;以及机构征收的任何其他与教育有关的收费或费用。指南实例为 LinguaPro Academy 语言中心——一家在吉隆坡提供法语教育的私立语言中心,向非公民收取的全年费用总额为 40,000 令吉,而该等向非公民提供的语言教育服务依服务税条例附表一第 M 组第 3 项属应税。此马来文版载有与四天后发布的英文版相同的实例。
13-06-2025 — Guidelines For Transition Of Sales Tax Rate Changes. The extracted text opens with the standard RMCD preface stating that the guide is intended to give a general understanding of the relevant treatment under sales legislation and of taxpayers' tax obligations, that it does not comprehensively address every possible tax issue that may arise, and that RMCD takes no responsibility for mistakes, inaccuracies or financial loss incurred by users. The preface notes that all information is current at the time of preparation and subject to change when necessary. Its table of contents, preserved in the extraction, shows the structure of the document: introduction; changes in the sales tax rate; saving on changes in the sales tax rate; and further sections. Because only the front matter was extracted, the transitional mechanics themselves are not summarised here.
13-06-2025 — 销售税税率变更过渡指南(Guidelines For Transition Of Sales Tax Rate Changes)。被提取的正文以关税局(RMCD)的标准前言开篇,说明本指南旨在让读者概括了解销售税法下的相关处理及纳税人的税务义务,并非全面处理所有可能出现的税务问题;RMCD 对使用者因使用本指南而产生的错误、不准确或财务损失概不负责。前言并指出,所有资料以编制时为准,并可能随时变更。提取内容中保留的目录显示文件结构:引言;销售税税率的变更;销售税税率变更的节省;以及后续章节。由于仅提取到前置部分,过渡机制本身此处不予概述。
13-06-2025 — Private Education Services. The provision of education-related services to non-citizens by higher education institutions registered under the Universities and University Colleges Act 1971, the Private Higher Educational Institutions Act 1996 and the Education Act 1996, and by language centres registered under the Education Act 1996, is subject to service tax on tuition fees, registration fees, admission charges, co-curricular charges, books and study materials charges, teaching aids or facilities charges, and any other charges or fees relating to education imposed by the institution. Services provided outside Malaysia fall outside the scope. The guide's example is LinguaPro Academy Language Centre in Kuala Lumpur, which provides French language education and charges non-citizens RM40,000 per annum in total fees, and the guide confirms that language education services to non-citizens are taxable under Item 3, Group M, First Schedule of the Service Tax Regulations.
13-06-2025 — 私立教育服务(Private Education Services)。由依 1971 年大学与大学学院法、1996 年私立高等教育机构法及 1996 年教育法注册的高等教育机构,以及依 1996 年教育法注册的语言中心,向非公民提供教育相关服务,须就学费、注册费、入学费、课外活动费、书籍与学习材料费、教具或设施费,以及机构征收的任何其他与教育有关的收费或费用缴纳服务税。在马来西亚境外提供的服务不属范围。指南实例为吉隆坡的 LinguaPro Academy 语言中心,该中心提供法语教育,向非公民收取全年费用总额 40,000 令吉;指南确认,向非公民提供的语言教育服务依服务税条例附表一第 M 组第 3 项属应税。
13-06-2025 — Rental Or Leasing Services. The guide sets out what falls outside the scope of service tax, beginning with the provision of rental or leasing services for a movable asset located outside Malaysia: a Malaysian company renting two harvesting machines located in Thailand to a Thai company for agricultural use is not subject to service tax, because the rental relates to a movable asset located outside Malaysia. The provision of rental or leasing services for housing accommodation is also outside the scope: a company leasing five condominium units to another company for staff accommodation is not subject to service tax, and neither is an individual renting a Small Office Home Office unit for residential purposes. The guide then turns to the provision of rental or leasing services between other parties, which is where the taxable cases begin.
13-06-2025 — 租赁服务(Rental Or Leasing Services)。指南逐一列出不属于服务税范围的情形,首先是就位于马来西亚境外的动产提供租赁服务:一家马来西亚公司将其位于泰国的两台收割机出租给一家泰国公司作农业用途,无须缴服务税,因为该租赁涉及位于境外的动产。为住房提供租赁或出租服务亦不属范围:一家公司向另一家公司出租五个公寓单位作员工住宿,无须缴服务税;个人为居住目的租用小型办公住宅(SOHO)单位,亦无须缴税。指南随后转向其他当事人之间的租赁服务,应税情形即自此开始。
19-06-2025 — Insurance and Takaful Services (Malay version only). Effective 1 September 2018, under Item 1, Group I, First Schedule of the Service Tax Regulations 2018, the provision of all types of insurance policies or takaful certificates by insurers or takaful operators licensed under the Financial Services Act 2013 [Act 758], the Islamic Financial Services Act 2013 [Act 759], the Labuan Financial Services and Securities Act 2010 [Act 704] and the Labuan Islamic Financial Services and Securities Act 2010 [Act 705] is subject to service tax. Effective 1 July 2025, this was amended to the provision of insurance or takaful services by any person regulated by Bank Negara Malaysia or by the Labuan Financial Services Authority, and the service was moved to Item 2, Group H (Financial Group), with effect from 1 July 2025. The guide therefore documents both the original licensing-based scope and its replacement by a regulator-based test.
19-06-2025 — 保险与回教保险服务(Insurance and Takaful Services,仅马来文版本)。自 2018 年 9 月 1 日起,依 2018 年服务税条例附表一第 I 组第 1 项,由依 2013 年金融服务法【第 758 号法令】、2013 年伊斯兰金融服务法【第 759 号法令】、2010 年纳闽金融服务与证券法【第 704 号法令】及 2010 年纳闽伊斯兰金融服务与证券法【第 705 号法令】持牌的保险公司或回教保险营运者提供的一切类型保险保单或回教保险证书,均须缴服务税。自 2025 年 7 月 1 日起,该条修订为由受马来西亚国家银行或纳闽金融服务局监管的任何人士提供保险或回教保险服务,且该服务自 2025 年 7 月 1 日起移至第 H 组(金融组)第 2 项。因此,本指南既记录了原先以持牌为基础的征税范围,也记录了其被以监管机构为基础的测试所取代。
20-06-2025 — Guide to Shariah Compliant Line of Credit or Financing Services Through Credit Card or Charge Card Activation (Malay version only). Effective 1 September 2018, the provision of credit card or charge card services by any person regulated by Bank Negara Malaysia became a taxable service under Group H, First Schedule of the Service Tax Regulations 2018. This was amended to the provision of Shariah compliant line of credit or financing services through the activation of a credit card or charge card, and moved to Item 1, Group H (Financial Group), effective 1 July 2025. The guide also notes that credit cards include co-branded credit cards and corporate cards, a co-branded card being one issued jointly by a card issuer and a merchant. It is the guide that explains the 2025 shift from conventional card services to Shariah compliant credit line and financing services.
20-06-2025 — 通过信用卡或签账卡激活提供符合回教教义信贷额度或融资服务指南(Guide to Shariah Compliant Line of Credit or Financing Services Through Credit Card or Charge Card Activation,仅马来文版本)。自 2018 年 9 月 1 日起,由受马来西亚国家银行监管的任何人士提供信用卡或签账卡服务,依 2018 年服务税条例附表一第 H 组成为应税服务。该条后被修订为通过激活信用卡或签账卡提供符合回教教义的信贷额度或融资服务,并自 2025 年 7 月 1 日起移至第 H 组(金融组)第 1 项。指南亦指出,信用卡包括联名信用卡及公司卡,联名卡是由发卡机构与商户共同发行的卡。正是这份指南说明了 2025 年由传统卡服务转向符合回教教义的信贷额度与融资服务的改变。
04-09-2025 — Group C, D and E Services (Malay version only). Service tax on the taxable services in Group C, First Schedule of the Service Tax Regulations 2018 applied to taxable persons from 1 September 2018, except karaoke centres, which became subject to service tax with effect from 26 February 2024. The services listed under Group C are night clubs, dance halls, cabarets, karaoke centres, wellness centres, massage houses, public houses and beer houses. From 1 September 2018, service tax also applied to the taxable services in Groups D and E for the taxable persons there listed, with Group D covering private clubs. The delayed start date for karaoke centres is the single most practically important detail in this guide for operators of those businesses.
04-09-2025 — C、D 及 E 组服务(Group C, D and E Services,仅马来文版本)。2018 年服务税条例附表一第 C 组的应税服务自 2018 年 9 月 1 日起对纳税人适用,惟卡拉 OK 中心除外,该等中心自 2024 年 2 月 26 日起方须缴服务税。第 C 组所列服务为:夜总会、舞厅、卡巴莱、卡拉 OK 中心、养生中心、按摩院、酒馆(公共酒吧)及啤酒屋。自 2018 年 9 月 1 日起,服务税亦对第 D 组及第 E 组所列纳税人的应税服务适用,其中第 D 组涵盖私人会所。对经营此类业务者而言,卡拉 OK 中心推迟起征日期是本指南中最具实际意义的细节。
09-09-2025 — Passenger Vehicle Rental Service (Malay version only). Passenger vehicle rental (Sewa Kenderaan Penumpang, SKP) refers to the provision of chauffeured car rental services, self-drive car rental services, charter bus services or excursion bus services. The guide sets out the treatment up to 30 June 2025: taxable passenger vehicle rental covers vehicles licensed under Section 18 of the Land Public Transport Act 2010 for public service vehicles — charter buses, rented cars, and rented chauffeured cars — and vehicles licensed under Section 38 of the same Act for tourist vehicle services, namely excursion buses and rented chauffeured cars for tourists. The four service types in the definition, and the section 18 and section 38 licensing divide, are the guide's operative content.
09-09-2025 — 载客车辆租赁服务(Passenger Vehicle Rental Service,仅马来文版本)。载客车辆租赁(Sewa Kenderaan Penumpang,SKP)指提供附司机的租车服务、自驾租车服务、包车巴士服务或观光巴士服务。指南列明截至 2025 年 6 月 30 日的处理方式:应税的载客车辆租赁涵盖依 2010 年陆路公共交通法第 18 条持牌的公共服务车辆——包车巴士、出租车辆及附司机出租车辆——以及依同一法律第 38 条持牌的旅游车辆服务,即观光巴士与供游客使用的附司机出租车辆。定义中的四类服务,以及第 18 条与第 38 条的发牌界线,构成本指南的实质内容。
27-10-2025 — Financial Services. The existing exemption for financial-related digital services in Group G, First Schedule of the Service Tax Regulations 2018 has been repealed and replaced with an exemption under Group H, First Schedule of the same Regulations, while the exemption for fees or commissions charged on local commodity trading platforms used exclusively for Islamic financial transactions remains unchanged. Financial services providers that also provide non-financial services categorised under Group G can still benefit from the group relief. The guide's example is Bank XY, a service tax registered financial services provider that also manages a sports complex and charges other companies, including those within the same group, for use of the facilities: both types of service are subject to tax, with financial management services falling under Group H and the rest under Group G. The example shows how the group relief operates when a financial institution's activities straddle the two groups.
27-10-2025 — 金融服务(Financial Services)。2018 年服务税条例附表一第 G 组中原有的金融相关数字服务免税,已被废除并由同一服务税条例附表一第 H 组下的免税取代;而就专用于伊斯兰金融交易的本地商品交易平台所收取的费用或佣金,其免税维持不变。同时提供属第 G 组类别的非金融服务的金融服务提供者,仍可享有集团减免。指南实例为 XY 银行:该行为注册服务税的金融服务提供者,除金融服务外亦管理一座体育中心,并向其他公司(包括同一集团内的公司)收取使用设施的费用;两类服务均属应税,其中金融管理服务归入第 H 组,其余归入第 G 组。此例显示当金融机构的活动横跨两组时,集团减免如何运作。
12-11-2025 — Guide on Sales Tax Exemption Under Item 33A, 33B, 55, 63, 64 & 65, Schedule A, Sales Tax (Persons Exempted From Payment of Tax) Order 2018. The extracted text is the guide's front matter: a preface explaining that the guide is intended to provide a general understanding of the relevant treatment under sales tax legislation and of taxpayers' obligations, that it is not intended to comprehensively address all possible tax issues, and that RMCD will not be responsible for mistakes, inaccuracies or financial loss arising from its use, all information being current at the time of preparation and subject to change. The table of contents preserved in the extraction shows that the guide is organised around introduction, terminology, conditions for sales tax exemption, and the effective time of exemption. The subject matter is therefore the exemptions granted under the five Schedule A items named in the title, rather than the charging provisions themselves.
12-11-2025 — 2018 年销售税(免缴税人士)令附表 A 第 33A、33B、55、63、64 及 65 项下的销售税免税指南(Guide on Sales Tax Exemption Under Item 33A, 33B, 55, 63, 64 & 65, Schedule A, Sales Tax (Persons Exempted From Payment of Tax) Order 2018)。被提取的正文为指南的前置部分:一段前言说明本指南旨在让读者概括了解销售税法下的相关处理及纳税人的义务,并非全面处理所有可能出现的税务问题;RMCD 对因使用本指南而产生的错误、不准确或财务损失概不负责;所有资料以编制时为准并可能变更。提取内容中保留的目录显示指南按引言、术语、销售税免税条件及免税生效时间编排。因此,其主题是标题所列附表 A 五个项目下授予的免税,而非征税条款本身。
29-12-2025 — Brokerage and Underwriting Services (Malay version only). The scope of brokerage services in relation to financial services includes the sale and purchase of securities and derivatives, insurance, money broking and other financial services industries. The guide explains the market structure: Bursa Malaysia is the principal regulator of the Malaysian capital market and is responsible for maintaining a fair and orderly market in securities and derivatives traded through its facilities, as well as orderly transactions in securities deposited with it and orderly, clear and efficient clearing and settlement arrangements for transactions cleared and settled through its facilities. Bursa Malaysia Securities Berhad (BMS) and Bursa Malaysia Derivatives Berhad (BMD) are wholly-owned subsidiaries of Bursa Malaysia Berhad and are responsible for providing, operating and maintaining the exchanges. Understanding who performs which function is the guide's starting point for deciding which brokers and underwriters are within scope.
29-12-2025 — 经纪与承保服务(Brokerage and Underwriting Services,仅马来文版本)。与金融服务有关的经纪服务范围,包括证券与衍生品的买卖、保险、货币经纪及其他金融服务行业。指南说明市场结构:马来西亚交易所(Bursa Malaysia)是马来西亚资本市场的主要监管机构,负责维持透过其设施交易的证券与衍生品市场公平有序,确保存放于其处的证券交易有序,并为透过其设施结算的交易提供有序、清晰且有效率的结算与交收安排。马来西亚证券交易所有限公司(BMS)与马来西亚衍生品交易所有限公司(BMD)为 Bursa Malaysia Berhad 的全资子公司,负责提供、营运及维持交易所。厘清各机构所执职能,是本指南判断哪些经纪与承保人属范围内的起点。
27-02-2026 — Information Technology Services (Malay version only). With effect from 1 September 2018, the provision of all types of information technology services by any person providing IT services became a taxable service under paragraph (h), column (2), Group G, First Schedule of the Service Tax Regulations 2018. With effect from 1 January 2020, IT services were extended to include distributing or reselling IT services on behalf of any person. Any taxable person in column (1), Group G whose total value of taxable services, aggregated or single, exceeds RM500,000 for any one or more of the taxable services specified in column (2) of that Group is liable to be registered under Section 13 of the STA 2018. The guide also defines information technology generally as the use of computers, storage, networking and physical devices, infrastructure and platforms — the base definition on which the rest of the guide builds.
27-02-2026 — 信息技术服务(Information Technology Services,仅马来文版本)。自 2018 年 9 月 1 日起,任何提供信息技术服务者所提供的所有类型信息技术服务,依 2018 年服务税条例附表一第 G 组第 (2) 栏第 (h) 段成为应税服务。自 2020 年 1 月 1 日起,信息技术服务扩展至包括代任何人分销或转售信息技术服务。第 G 组第 (1) 栏的任何应税人,若就该组第 (2) 栏所列任何一项或多项应税服务的应税服务总值(合并或单项)超过 500,000 令吉,即须依 2018 年服务税法第 13 条注册。指南亦概括地将信息技术定义为电脑、存储、网络及实体设备、基础设施与平台的使用——这是指南其余内容所依据的基础定义。
01-03-2026 — Private Healthcare Services (Malay version only). Within the scope of service tax, healthcare services provided to non-citizen patients are subject to service tax. Under column (1), item 14, Group I, a taxable person is any person who operates or provides a private healthcare facility registered or licensed under the Private Healthcare Facilities and Services Act 1998 [Act 586], excluding any university or university college registered under the Universities and University Colleges Act 1971 [Act 30] or the MARA University of Technology Act 1976 [Act 173] that operates or provides a private healthcare facility, and excluding specified private healthcare facilities including the University of Malaya Specialist Centre, the National University of Malaysia Specialist Centre and the Universiti Teknologi MARA Medical Specialist Centre. The citizen/non-citizen line and the institutional exclusions together define the tax base.
01-03-2026 — 私人医疗服务(Private Healthcare Services,仅马来文版本)。在服务税范围内,向非公民病患提供的医疗服务须缴服务税。依第 I 组第 (1) 栏第 14 项,应税人指任何经营或提供依 1998 年私人医疗设施与服务法【第 586 号法令】注册或持牌的私人医疗设施的人,但不包括依 1971 年大学与大学学院法【第 30 号法令】或 1976 年玛拉工艺大学法【第 173 号法令】注册、且经营或提供私人医疗设施的大学或大学学院,亦不包括特定私人医疗设施,例如马来亚大学专科中心、马来西亚国民大学专科中心及玛拉工艺大学医学专科中心。公民与非公民之分,加上机构排除条款,共同界定了税基。
AMENDMENT — 17-03-2026 — Guide on Construction Work Services (Amendment). The extracted text is the amended portion of the construction work services guide, updated as at 17 March 2026, dealing with residential building construction. The developer or property owner must submit to the main contractor either a pre-computation plan (pre-comp plan) or an approved planning permission letter issued by the local authority, and the developer or property owner and the main contractor must comply with any general directive issued by the Director General of Customs. The amendment also sets out the apportionment method for mixed development of residential and non-residential buildings, using Example 8 in which the contract value is 30,000,000, the value of building materials is 19,000,000 and the value of construction work services is 11,000,000, against a built-up area of 650,000 sq ft split between residential and non-residential portions.
修订——17-03-2026 — 建筑工程服务指南(修订)(Guide on Construction Work Services (Amendment))。被提取的正文为建筑工程服务指南的修订部分,更新至 2026 年 3 月 17 日,内容涉及住宅建筑建造。开发商或业主须向总承包商提交预先计算计划(pre-comp plan),或地方当局发出的已批准规划许可函;开发商或业主与总承包商并须遵守关税局总监发出的任何一般指示。该修订亦列明住宅与非住宅建筑混合开发的分配方法,并以实例 8 说明:合约价值为 30,000,000,建筑材料价值为 19,000,000,建筑工程服务价值为 11,000,000,建筑总面积为 650,000 平方英尺,并按住宅与非住宅部分划分。
AMENDMENT — 19-03-2026 — Construction Work Services. The extracted text carries the same amended content as the 17 March 2026 amendment guide, updated as at 17 March 2026, so the re-issued guide again covers residential building construction: the developer or property owner must submit to the main contractor either a pre-computation plan (pre-comp plan) or an approved planning permission letter issued by the local authority, and both the developer or property owner and the main contractor must comply with any general directive issued by the Director General of Customs. It repeats the apportionment method for mixed development of residential and non-residential buildings through Example 8, where the contract value is 30,000,000, building materials are 19,000,000, construction work services are 11,000,000 and the built-up area is 650,000 sq ft. The re-issue is dated two days after the amendment guide and describes the same amended scope, responsibilities, types of residential building construction, technical specifications and pricing.
修订——19-03-2026 — 建筑工程服务(Construction Work Services)。被提取的正文载有与 2026 年 3 月 17 日修订指南相同的修订内容,更新至 2026 年 3 月 17 日;因此这份重新发布的指南再次涵盖住宅建筑建造:开发商或业主须向总承包商提交预先计算计划(pre-comp plan),或地方当局发出的已批准规划许可函;开发商或业主与总承包商均须遵守关税局总监发出的任何一般指示。指南以实例 8 重述住宅与非住宅建筑混合开发的分配方法:合约价值为 30,000,000,建筑材料为 19,000,000,建筑工程服务为 11,000,000,建筑总面积为 650,000 平方英尺。该重新发布件日期为修订指南之后两天,所述修订范围、责任、住宅建筑建造类型、技术规格与定价均相同。
17-04-2026 — Electricity Transmission and Distribution Services (Malay version only). The guide covers the taxable services under Item 9, Group I, First Schedule of the Service Tax Regulations 2018, namely the transmission and distribution of electricity. Its FAQ addresses whether an entity holding a Public Distribution Licence (LAP) is subject to service tax and answers that it is not: an entity holding an LAP under Section 9(1)(b) of the Electricity Supply Act 1990 buys electricity from a main supplier such as TNB and distributes it directly to commercial users without involving an electricity transmission service. The guide closes with a contact point for enquiries, directing questions about the guide to the relevant division of the Customs Department. This later version repeats the licence-based distinction already drawn in the 2021 version.
17-04-2026 — 电力输送与配电服务(Electricity Transmission and Distribution Services,仅马来文版本)。指南涵盖 2018 年服务税条例附表一第 I 组第 9 项下的应税服务,即电力的输送与配电。其常见问题部分探讨持有公共配电执照(LAP)的实体是否须缴服务税,答案是“否”:依 1990 年电力供应法第 9(1)(b) 条持有 LAP 的实体,向主要供应商(如国能 TNB)购电并直接配电给商业用户,不涉及电力输送服务。指南末尾附有查询联络方式,指引读者就本指南的问题联系关税局相关部门。这一较新版本重复了 2021 年版已作出的、以执照为界的区分。
07-05-2026 — Management Services. Under subsection 10(2) of the STA 2018, the Minister of Finance determined that the service tax rate increased from 6% to 8% effective 1 March 2024 on all taxable services except those specified in the First Schedule and Second Schedule of the Service Tax (Rate of Tax) Order 2018, so the provision of management services is subject to service tax at 8% from that date. The taxable management services listed under item (i), column (2), Group G, First Schedule of the STR 2018 include project management services, full or part of the project, carried out by any person who manages a project in full or in part. For the transitional treatment of rate changes the guide refers readers to the service tax rate change transition guide. Apart from the date of publication, the substantive text repeats the 2021 edition.
07-05-2026 — 管理服务(Management Services)。依 2018 年服务税法第 10(2) 条,财政部长决定自 2024 年 3 月 1 日起,对所有应税服务的服务税税率由 6% 提高至 8%,惟 2018 年服务税(税率)令附表一及附表二所列服务除外;故提供管理服务自该日起按 8% 缴纳服务税。2018 年服务税条例附表一第 G 组第 (2) 栏第 (i) 项所列应税管理服务,包括由任何就整个或部分项目进行管理的人所提供的、整个或部分项目的项目管理服务。就税率变更的过渡处理,指南指引读者参阅服务税税率变更过渡指南。除发布日期外,其实质正文与 2021 年版相同。
14-05-2026 — Rental or Leasing Services (Malay version only). The extracted text is the English-language scope section on what is outside the scope of service tax. Providing rental or leasing services for a movable asset located outside Malaysia is outside the scope: Example 10 has Syarikat APX Malaysia Sdn Bhd renting two units of its harvesting machine located in Thailand to Predator Co. Ltd., based in Pattani, Thailand, for agricultural use, and that rental is not subject to service tax because the movable asset is located outside Malaysia. Providing rental or leasing services for housing accommodation is also outside the scope: in Example 11, TPS Sdn Bhd leases five condominium units to LGU Sdn Bhd for employee accommodation, which is not subject to service tax, and in Example 12 Ahmad rents a SOHO unit from POY Properties Sdn Bhd for residential purposes, which is likewise not taxable. The guide then proceeds to the provision of rental or leasing services between other parties. The same scope text and examples appeared in the English-language guide dated 13 June 2025.
14-05-2026 — 租赁服务(Rental or Leasing Services,仅马来文版本)。被提取的正文为英文撰写的范围部分,说明何者不属服务税范围。就位于马来西亚境外的动产提供租赁或出租服务不属范围:实例 10 中,Syarikat APX Malaysia Sdn Bhd 将其位于泰国的两台收割机出租给总部设于泰国北大年的 Predator Co. Ltd. 作农业用途,该租赁无须缴服务税,因该动产位于马来西亚境外。为住房提供租赁或出租服务亦不属范围:实例 11 中,TPS Sdn Bhd 向 LGU Sdn Bhd 出租五个公寓单位作员工住宿,无须缴服务税;实例 12 中,Ahmad 向 POY Properties Sdn Bhd 租用 SOHO 单位作居住用途,同样不属应税。指南随后进入其他当事人之间的租赁或出租服务。相同的范围正文与实例亦见于 2025 年 6 月 13 日的英文版指南。
05-06-2026 — Vehicle Parking Services (Malay version only). Vehicle parking space (Ruang Letak Kenderaan, RLK) comprises two categories. On-street parking is parking provided within the road reserve (ROW), using part of the road area, whether paved or unpaved, and must be clearly marked and regulated by the local authority. Off-street parking is parking space outside the road reserve, including within a building or on specifically allocated sites. The guide also sets out the payment systems used for parking spaces, which include single or centralised meters, tickets or coupons, and smart cards, and it begins to address the methods of payment. The two-category structure and the payment-system detail are what the guide uses to identify the operator and the charge that become the basis of the service tax.
05-06-2026 — 停车位服务(Vehicle Parking Services,仅马来文版本)。停车位(Ruang Letak Kenderaan,RLK)分为两类。路旁停车指在道路保留地(ROW)内提供的停车设施,使用部分道路范围(无论铺装与否),须清楚标示并由地方当局监管。路外停车指道路保留地以外的停车位,包括建筑物内或特别划定的场地。指南亦列出停车位所用的缴费系统,包括单表或中央收费表、票券或回数券,以及智能卡,并开始说明缴费方式。指南正是借助这两类结构及缴费系统细节,来识别营运者及构成服务税基础的收费。
10-06-2026 — General Service or Motor Vehicle Repair (Malay version only). A motor vehicle service or repair centre, also known as a garage or workshop, is a place where motor vehicles are serviced or repaired. General service or motor vehicle repair services are not restricted to being carried out at a service or repair centre and may be carried out on a mobile basis from any location. The service tax rate for general service or motor vehicle repair services is 8%, and the cost of spare parts is not subject to service tax. The taxable services are those listed under item 5, Group I, First Schedule of the Service Tax Regulations 2018. The mobile-service point and the exclusion of spare parts costs are the two details that most directly change how a workshop computes the tax on an invoice.
10-06-2026 — 一般维修或机动车维修服务(General Service or Motor Vehicle Repair,仅马来文版本)。机动车维修或服务中心(亦称修车厂或工场)是对机动车进行保养或维修的场所。一般维修或机动车维修服务并不限于在服务中心或维修中心内进行,亦可从任何地点以流动方式提供。一般维修或机动车维修服务的服务税税率为 8%,零件成本无须缴服务税。应税服务为 2018 年服务税条例附表一第 I 组第 5 项所列者。流动提供服务的要点,以及零件成本不计入税基,是两项最直接影响工场如何计算发票税额的细节。
What changed — Rental Or Leasing (14-05-2026 → 13-06-2025)
| Item | Old version | New version | Change |
|---|
变更内容——Rental Or Leasing(14-05-2026 → 13-06-2025)
| 项目 | 旧版 | 新版 | 变更 |
|---|
What changed — Management (07-05-2026 → 04-08-2021)
| Item | Old version | New version | Change |
|---|
变更内容——Management(07-05-2026 → 04-08-2021)
| 项目 | 旧版 | 新版 | 变更 |
|---|
What changed — Electricity Transmission And Distribution (17-04-2026 → 04-08-2021)
| Item | Old version | New version | Change |
|---|
变更内容——Electricity Transmission And Distribution(17-04-2026 → 04-08-2021)
| 项目 | 旧版 | 新版 | 变更 |
|---|
What changed — Construction Work (17-03-2026 → 19-03-2026)
| Item | Old version | New version | Change |
|---|
变更内容——Construction Work(17-03-2026 → 19-03-2026)
| 项目 | 旧版 | 新版 | 变更 |
|---|
What changed — Private Education (13-06-2025 → 09-06-2025)
| Item | Old version | New version | Change |
|---|
变更内容——Private Education(13-06-2025 → 09-06-2025)
| 项目 | 旧版 | 新版 | 变更 |
|---|
What changed — Logistic (06-06-2025 → 26-02-2024)
| Item | Old version | New version | Change |
|---|
变更内容——Logistic(06-06-2025 → 26-02-2024)
| 项目 | 旧版 | 新版 | 变更 |
|---|
MyTax Info
More practical e-Invoice updates